
Seasonal Guide: Preparing Your Finances for a Mortgage Renewal in Ontario
Understanding Mortgage Renewal
In Ontario, when your mortgage term comes to an end, you'll face the decision of renewing it. This process can seem daunting, but with the right preparation, you can make informed choices that align with your financial goals. Understanding the basics of mortgage renewal is the first step towards a smooth transition.
Mortgage terms in Ontario typically last from one to five years. At the end of each term, you have the opportunity to renew your mortgage with your current lender or explore other options. It's crucial to begin preparations well before your term's end date to ensure you secure the best possible terms.

Assessing Your Financial Situation
Before renewing your mortgage, take a thorough look at your current financial situation. Calculate your income, expenses, and any changes that might have occurred since you last negotiated your mortgage. This will provide a clear picture of what you can afford in terms of monthly payments.
Review your credit score as well. A strong credit score can open doors to better rates and terms. If your score has improved, you may be in a better position to negotiate more favorable conditions.
Debt Management
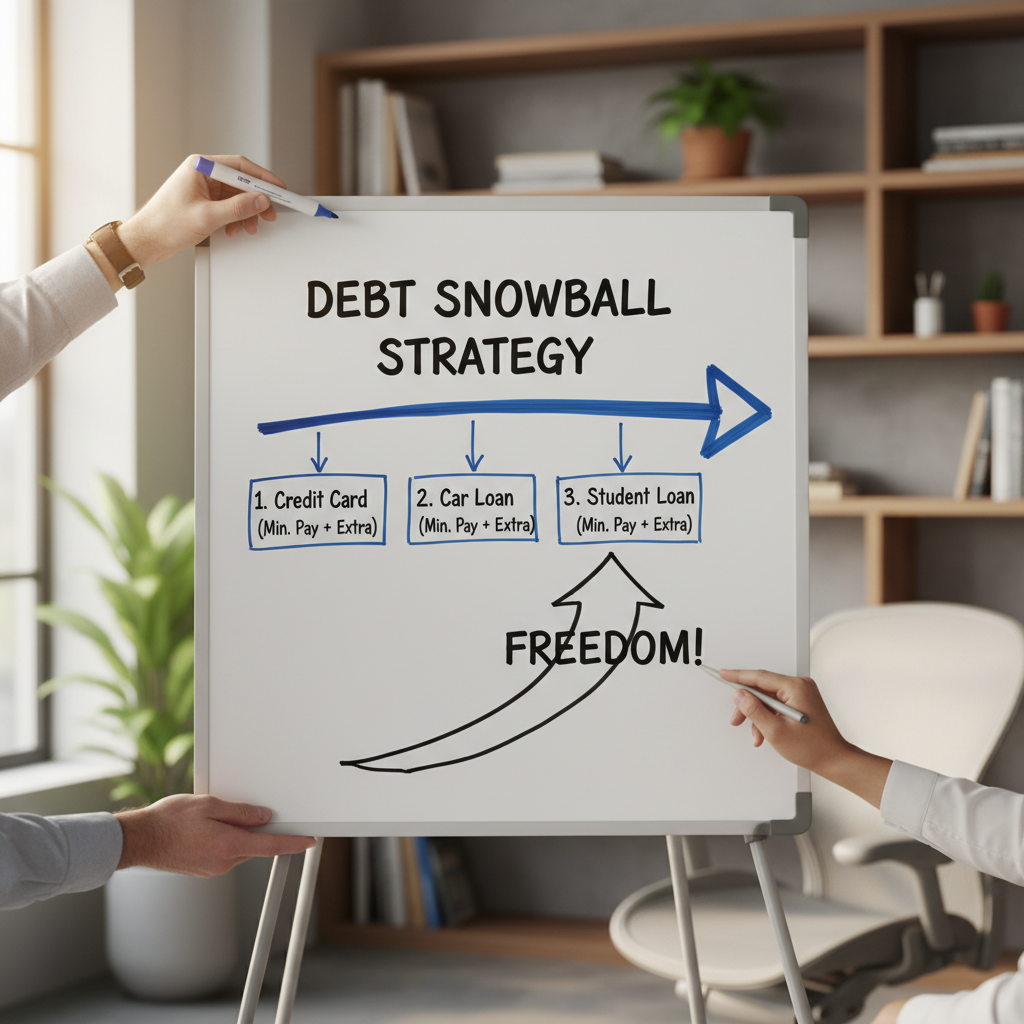
Managing existing debts is another critical aspect of preparing for mortgage renewal. Consider paying down high-interest debts to improve your financial standing. This can positively impact your debt-to-income ratio, making you a more attractive candidate for lenders.
Exploring Renewal Options
As your mortgage renewal date approaches, you should explore various options. While renewing with your current lender might seem convenient, other lenders may offer more competitive rates or terms. It pays to shop around and compare offers.
Engage with a mortgage broker if you feel overwhelmed by the options. They can provide expert advice and help you navigate the complexities of mortgage products available in the market.
Fixed vs. Variable Rates
One of the significant decisions you'll face is whether to go with a fixed or variable rate mortgage. Fixed rates offer stability, as your payments remain constant throughout the term. Variable rates, on the other hand, can fluctuate with market conditions, potentially offering savings if rates decrease.

Negotiating Better Terms
Don't be afraid to negotiate with your lender for better terms. Highlight any positive changes in your financial situation, such as increased income or improved credit score, to strengthen your negotiating position. Remember, lenders want to retain good customers.
Consider negotiating for additional benefits, such as reduced fees or flexible payment options, to make your mortgage work better for your lifestyle.
Finalizing Your Decision
Once you've explored your options and negotiated terms, it's time to finalize your decision. Ensure you understand all the details of your new mortgage agreement, including any fees or penalties for early repayment.
Taking the time to prepare and research can lead to significant savings and a mortgage that better fits your financial goals. With careful planning, you can navigate your mortgage renewal in Ontario with confidence.